
A few years ago the FIRE movement promised something bold. Save hard, invest simply, and walk away from work in your forties. The internet filled with stories of people who pulled it off. Then prices rose about 27 percent from the start of 2021. The personal savings rate fell to 4.1 percent in August 2026, the lowest recorded since 2022. And in a May 2026 survey, 71 percent of workers said FIRE now feels unrealistic for most people.
So is FIRE dead? The fantasy version is struggling. But the goal underneath it, buying back your time, is still alive. The original playbook assumed costs you could control and growth you could count on. Life in 2026 looks different. A smarter, more flexible version of the movement is already taking shape, and it fits real households far better.
What the Numbers Are Really Saying
The fear around retirement is at a record high. The October 2026 Retirement Fear Index reached 124.2, a new all time high and its largest single month jump since the index launched. The theme driving it has a name. Competing priorities.
New research from Goldman Sachs found retirement savings momentum fell from 55 percent to 39 percent in one year. Seventy percent of workers have deferred a major financial goal because of daily expenses. Sixty two percent are financially supporting family members. Fifty eight percent are paying down credit card debt. Two thirds of workers across generations expect to delay retirement because other demands keep claiming the money first.
Read that list one more time. The problem is not laziness and it is not bad math. It is a household budget with five urgent claims on every dollar. Money meant for the future gets spent on the present, on family, on debt, on a grocery bill that never stops climbing. Telling people in that situation to simply save more is not advice. It is noise.
Why the Classic FIRE Formula Breaks Down
The classic FIRE formula was simple. Save 50 to 70 percent of your income. Put it in index funds. Once you have about 25 times your annual spending saved, withdraw 4 percent a year and never work again.
Elegant math. But three things broke it for most households.
First, inflation crushed the savings rate. Consumer prices are up about 27 percent since the start of 2021. When every bill costs more, saving half your paycheck is fantasy for anyone earning an ordinary income. The savings rate data proves it. Americans saved only 4.1 percent of disposable income in August 2026.
Second, the 4 percent rule was designed for a traditional retirement, not one that might last fifty years. Starting withdrawals at forty leaves decades for markets to misbehave and inflation to compound. A rule built for thirty years of spending gets shaky stretched to fifty.
Third, classic FIRE treated housing and health care as background details. In 2026 they are the main event. Mortgage rates crossed 7 percent. Rents keep climbing. And one serious medical bill can erase years of careful saving. You cannot spreadsheet your way around costs that big.
The New Flavors of FIRE That Fit Real Life
The movement did not die. It grew up. The new versions are more honest about how real life works, and each one solves a different piece of the puzzle.
Coast FIRE
Save aggressively while you are young, then stop contributing and let compounding finish the job. A 33 year old with five hundred thousand dollars invested could walk away from saving entirely and still watch it grow into millions by 65 at typical market returns. Coast FIRE says you do not have to sprint forever. You just have to start early enough that time does the heavy lifting.
Barista FIRE
Retire from the career, not from work. Leave the demanding job and cover the gap with lighter work that keeps you insured and engaged while your investments keep growing. It answers the hardest question in early retirement planning, how to fund health care and daily life for decades without a full time salary.
Lean FIRE and Fat FIRE
Same math, different finish lines. Lean FIRE accepts a simpler lifestyle to reach freedom sooner. Fat FIRE builds a much bigger number to fund a richer one. The lesson underneath both is the one that matters. Your spending sets your timeline. Every dollar you do not need is a dollar you do not have to save. Control your spending and you control the clock.
A Realistic Freedom Plan for 2026
You do not need to pick a label. You need a plan that survives contact with real bills. Here is one built for the economy you actually live in.
1. Capture every free dollar first
If your employer matches retirement contributions, contribute enough to earn the full match. That match is an instant return no market can promise you. Then fund a Roth IRA with whatever you can. Money that grows inside a Roth can be withdrawn in retirement without another tax bill, which makes it one of the most powerful tools a younger saver has.
2. Automate a rate you can keep
Forget saving half your income. Pick a rate you can sustain without thinking about it, then raise it by one point every time you get a raise. A steady 15 to 20 percent on autopilot beats a heroic 50 percent that collapses after six months.
3. Give your cash a raise
Savings accounts are paying up to 5 percent after the recent Fed moves. Money sitting in a checking account earning next to nothing is a pay cut you chose. Move your emergency fund to a high yield account today. Our breakdown of the recent Fed rate hike shows exactly how savers can claim the upside.
4. Destroy the debt that eats your future
Credit card debt at 20 percent or more is a fire aimed directly at your savings. List every balance from highest rate to lowest. Throw every spare dollar at the top of the list while paying minimums on the rest. Each balance you clear is a raise you give yourself, and it is tax free.
5. Buy assets before lifestyle
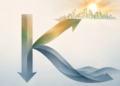
In the K shaped economy we are living through, owners pull ahead and earners fall behind. The fix is to become an owner as early as you can. See why net worth accelerates after one hundred thousand dollars to understand the compounding curve you are climbing. Slow at first. Unstoppable later. Every dollar that buys an income producing asset instead of a depreciating one moves you to the upward arm.
Your One Move This Week
Information without action is entertainment. Here is your assignment before next weekend.
Open your retirement account and raise your contribution by one percent. You will barely feel it in your paycheck, and you will have started the only habit that matters. Then set a reminder to raise it one more point at your next raise.
You do not have to retire at forty to win. You just have to move toward freedom instead of drifting away from it. One percent today. One more point at your next raise. That is how ordinary paychecks build extraordinary futures.
The FIRE movement is not dead. The fantasy is. What replaces it is better. A plan you can actually keep, built for the economy you actually live in.
Want the full roadmap to financial freedom? Download the free UnlockedFi ebook. It is short, practical, and built for real households. Grab your copy today and start building your plan.