
The internet just gave you permission to save less. Read the fine print.
Something strange is happening in personal finance right now. A generation that watched housing prices sprint away from wages, watched groceries climb while paychecks crawled, and watched the dream of retiring at forty fade into a meme has decided to stop punishing itself. The trend is called soft saving. Instead of grinding for a future that feels out of reach, you save a little less and live a little more today.
On the surface, it sounds healthy. After years of hustle culture telling young workers to skip the coffee, skip the vacation, and invest every spare cent, a little softness feels like a correction. And in one way, it is. I have spent twenty one years as an insurance broker and twenty as a real estate broker watching families in Florida build wealth, and watching others watch wealth slip away. The pattern is clear. The people who win are not the ones who suffer the most. They are the ones who build a plan they can actually keep.
But soft saving has a trap door, and it opens quietly. Let me show you where it is, and how to enjoy today without borrowing from tomorrow.
What soft saving really means
Soft saving is the idea that you ease off the extreme saving pedal. Instead of saving half your income or chasing early retirement, you save at a gentler pace and spend more on the life in front of you. Trips, dinners, experiences. The philosophy says your twenties and thirties only happen once.
The trend grew for a reason. Prices have outrun paychecks for years. Goldman Sachs surveyed American workers this year and found retirement savings momentum dropped from fifty five percent to thirty nine percent in a single year. When the old rules feel impossible, people rewrite them.
Here is the problem. The economy did not soften just because your savings plan did. Credit card balances in America just hit one point two six trillion dollars, according to the Federal Reserve Bank of New York. Borrowers seventy and older just posted their worst card delinquency numbers in fifteen years. One in three workers in a recent retirement survey carries more credit card debt than retirement savings. Saving less in this environment can work, but only with your eyes wide open.
The difference between soft saving and soft spending
This is the lesson that matters, so read it twice.
Soft saving means you spend with a plan and you save on purpose, just at a slower rate. Soft spending means you call lifestyle inflation a philosophy. The difference shows up in one place: the balance sheet. If your net worth is rising year after year, even slowly, you are soft saving. If your credit card balances are rising while your savings stay flat, you are soft spending and dressing it in a trendier name.
A creator online put it perfectly. She said she does not want a soft life funded by hard debt. She wants the trips and the dinners and the experiences AND the investments and the emergency fund and the retirement accounts to match. That is the whole game in one sentence. Enjoyment funded by cash is freedom. Enjoyment funded by a credit card at twenty two percent interest is a bill your future self cannot afford, and it will arrive with fees.
I have watched too many families learn this late. The regret is never the vacation they took. It is always the debt they took to take it. Money spent from savings creates memories. Money spent from a credit card creates a payment that eats every memory that came after.
The soft saving rules that actually work
If you like the spirit of soft saving, here is how to do it without sinking the ship. These are the rules I would hand my own clients.
1. Never soften the free money
If your employer matches retirement contributions, contribute enough to earn the full match before you spend one extra dollar on lifestyle. That match is an instant return that no market and no trend can promise. It is about saving less than the extreme plans demand, not about leaving free money on the table.
2. Set a floor you will not go under
Pick a savings rate that feels almost too easy, then automate it so you never have to think about it. For most people that floor is ten percent of every paycheck, plus the employer match on top. A gentle ten percent on autopilot will beat an aggressive forty percent that collapses every February. Rethinking early retirement taught us the same lesson. The fantasy is not the goal. A plan you can keep is the goal.
3. Budget for joy on purpose
Put your fun money in the budget as a line item, right next to rent and groceries. When joy has a budget, it stops being a leak. A dinner out that you planned feels completely different from a dinner out that you financed. One is living. The other is borrowing.
4. Kill the expensive debt first
Soft saving cannot survive credit card interest. At twenty percent and above, your balances grow faster than any lifestyle can justify. List every balance from highest rate to lowest, pay minimums on all but one, and throw every spare dollar at the top of the list.
5. Buy assets before lifestyle upgrades
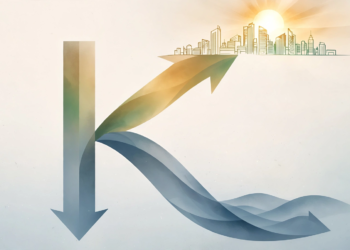
We are living through what economists call the K shaped economy, where owners pull ahead and earners fall behind. The escape hatch is becoming an owner as early as you can. This is also why net worth takes off after one hundred thousand dollars. The climb is slow at first, then it compounds into something that looks like magic. Every dollar that buys an income producing asset moves you to the upward arm of the K.
6. Use the thirty day list
Before any purchase that is not essential, write it on a list and wait thirty days. If you still want it after thirty days and it fits the joy budget, buy it with a clear conscience. Most of the time you will forget the item entirely, which tells you everything about how badly you wanted it.
Your one move this week
Information without action is entertainment, so here is your assignment before next weekend.
Open your bank app and automate a transfer of ten percent of your next paycheck into a separate account. Then add one line to your budget called joy, fund it with a number you can defend, and spend every dollar of it without guilt.
That is soft saving done right. A future that keeps growing and a present that feels worth living. You do not need to choose between them. You just need a plan that protects both.
Want the full roadmap to financial freedom? Download the free UnlockedFi ebook. It is short, practical, and built for real households. Grab your copy today and start building your plan.